العودة إلى الصفحة الرئيسية

الأكثر مبيعاً ليس بالضرورة الأكثر ربحية
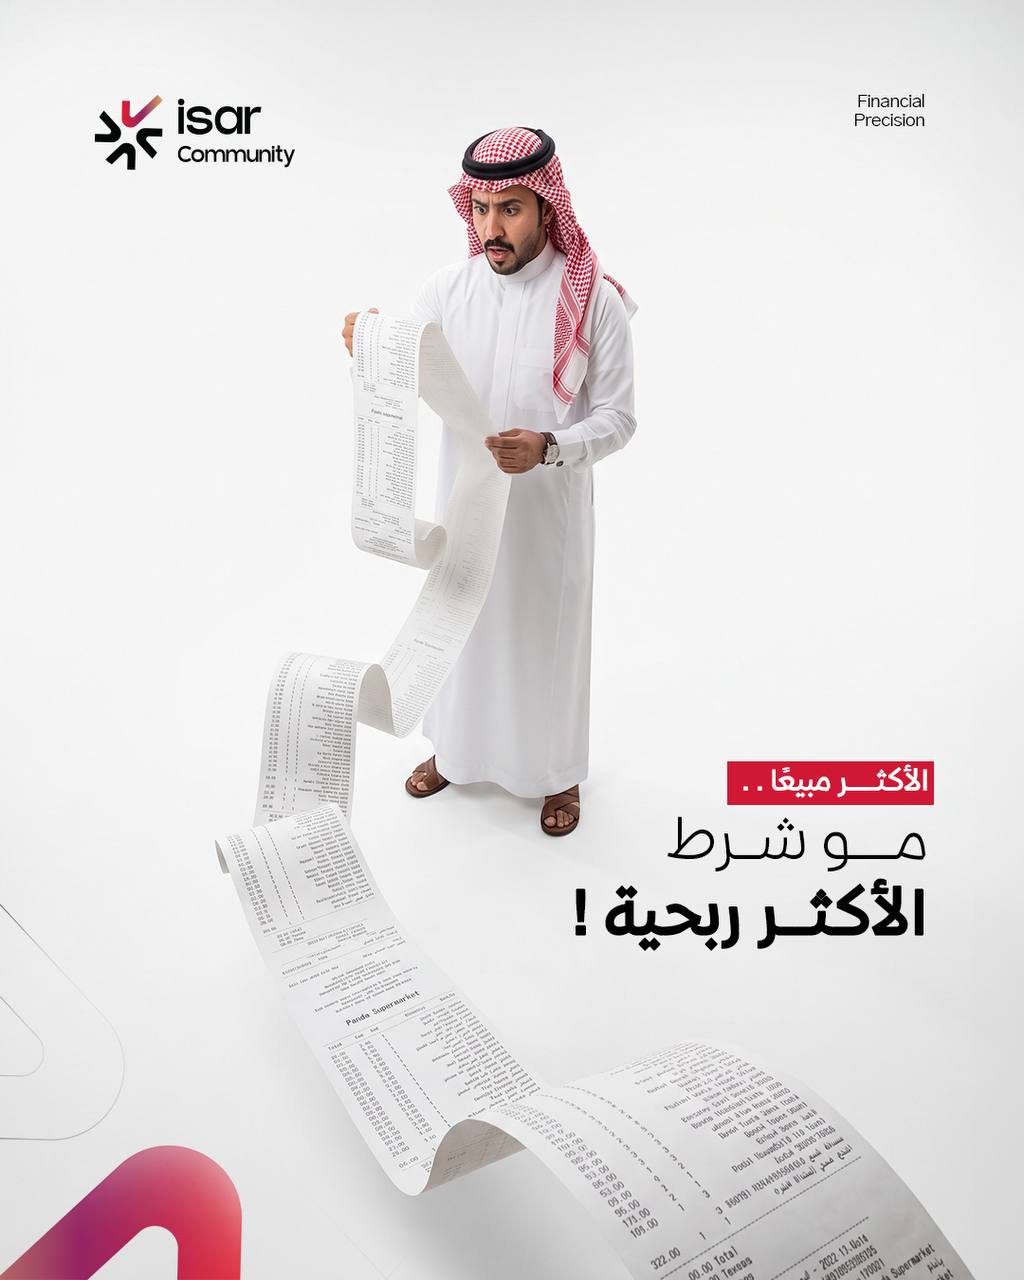
الأكثر مبيعاً ليس بالضرورة الأكثر ربحية
ينجذب كثير من الرؤساء التنفيذيين ومسؤولي المبيعات إلى ارتفاع الإيرادات، وتوالي الفواتير، وزيادة حركة البضائع. لكن مراجعة الحسابات قد تكشف أن المنتج «الأكثر مبيعاً»، الذي يستهلك جزءاً كبيراً من وقت الشركة ومواردها، يسهم في تراجع صافي الأرباح بدلاً من دعمها.

وهم حجم المبيعات (The Volume Illusion): حينما تكون المبيعات فخاً

في عالم الأعمال، لا تكفي الإيرادات وحدها لتقييم أداء المنتج؛ إذ ينبغي النظر إلى صافي الربح بعد احتساب التكاليف. وقد يؤدي الاعتماد على الأسعار المنخفضة أو الخصومات المفرطة إلى خفض هامش المساهمة، وربما جعله سلبياً بعد احتساب التكاليف التشغيلية.

التكاليف الخفية التي تلتهم هامش الربح دون أن تشعر

عند حساب تكلفة المنتج، قد تقتصر بعض الشركات على سعر الشراء أو المواد الخام، بينما توجد تكاليف أخرى ينبغي أخذها في الحسبان، منها:

  • تكلفة التمويل والسيولة المحبوسة: يتطلب شراء كميات كبيرة من المنتجات وتخزينها سيولةً وتسهيلاتٍ مصرفية، وتزداد تكلفة التمويل مع ارتفاع معدلات سايبور (SAIBOR).
  • تكاليف الخدمات اللوجستية والمناولة: التخزين والنقل والمرتجعات والتلف، وهي تكاليف قد تزداد مع ارتفاع عدد الوحدات المباعة.
  • حوافز وخصومات التوزيع: الخصومات التراكمية الممنوحة لكبار المشترين ومنافذ التجزئة، والتي تقتطع الجزء الأكبر من هامش الربح الإجمالي.
  • تكلفة الفرصة البديلة (Opportunity Cost): انشغال فريق العمليات وخدمة العملاء بالمنتجات منخفضة الهامش، بدلاً من توجيه بعض الجهود إلى المنتجات الأعلى قيمة مضافة.

«لا يقتصر تقييم الأداء على حجم المبيعات؛ بل يشمل ما يتبقى بعد احتساب التكاليف. فالنمو دون ربحية قد يعرّض استدامة الشركة للخطر.»

— وحدة الاستشارات المالية وتحليل الربحية، ISAR COMMUNITY

أداة الحل: مصفوفة ربحية الوحدة (Unit Economics) وهامش المساهمة

لكي تستعيد شركتك زمام السيطرة على أرباحها، يجب تبني منهجية تحليل هامش المساهمة (Contribution Margin) لكل صنف على حدة:

  1. تفكيك التكلفة الحقيقية للوحدة: احتساب التكاليف المباشرة وغير المباشرة وتخصيص مصاريف الشحن والمستودعات والعمولات لكل وحدة مباعة.
  2. تصنيف المنتجات حسب الربحية: فرز منتجاتك إلى ثلاث فئات واضحة:
    • منتجات القيمة (Value Drivers): ربحيتها عالية حتى لو كان حجم مبيعاتها متوسطاً.
    • منتجات متوازنة: تحقق ربحاً معقولاً وتساهم في تغطية المصاريف الثابتة.
    • أفخاخ السيولة (Cash Traps): منتجات تبيع بكثافة لكنها تخسر مع كل عملية بيع بعد احتساب المصاريف التشغيلية.
  3. إعادة هندسة التسعير: التوقف عن التسعير المبني على العواطف أو مجرد مجاراة المنافسين، والتحول إلى التسعير القائم على القيمة وهامش الربح المستهدف.

كيف تحل ISAR COMMUNITY هذه المعضلة لشركتك؟

في ISAR COMMUNITY، لا نكتفي بقراءة القوائم المالية من الخارج، بل نغوص في التفاصيل الدقيقة لعملياتك التشغيلية ومصفوفة منتجاتك:

  • التدقيق المالي الشامل للتكاليف (Cost Structure Audit): نحدد بدقة متناهية أين تتسرب أرباحك، وأي المنتجات تدعم الشركة فعلياً وأيها يمثل عبئاً خفياً.
  • إعادة تصميم استراتيجية التسعير وهوامش الربح: نساعدك في وضع سياسات تسعير مرنة تدعم حماية هوامشك الصافية في مواجهة التضخم وتقلبات التكاليف.
  • إعادة توجيه الموارد التسويقية والبيعية: تمكين فريقك من تركيز الجهد والتمويل على المنتجات والخدمات التي تولد أقصى عائد على رأس المال المستثمر (ROIC).

هل تبيع منتجاتك بأرقام ضخمة ولا تجد عائداً مجزياً في صافي أرباحك؟

يقدم فريق ISAR COMMUNITY تشخيصاً لمحفظة منتجاتك لتحديد مواطن تراجع الربحية ومراجعة التسعير وهيكل التكاليف.

احجز استشارة تحليل الربحية الآن

Best-Selling Doesn't Mean Most Profitable: The Margin Trap

Best-Selling Doesn't Mean Most Profitable: The Margin Trap
Many CEOs and commercial leaders focus on top-line revenue, invoices, shipping activity, and warehouse turnover. But reviewing the annual accounts may reveal that a popular product consumes significant operational resources while contributing little to net profit.

The Volume Illusion: When Sales Growth Becomes a Trap

In corporate finance, there is a golden rule often overshadowed by vanity metrics: "Revenue is vanity, profit is sanity, but cash is reality." Commercial teams naturally gravitate toward products that sell easily and quickly. However, velocity is frequently bought with deep discounting or razor-thin pricing, leaving a contribution margin near zero—or even negative once operational and carrying overheads are allocated.

Hidden Costs Consuming Your Margins in Plain Sight

When companies evaluate unit costs, they typically count only direct procurement or raw materials (COGS). A forensic cost accounting audit reveals hidden expenses that quietly erode the bottom line:

  • Financing and Trapped Capital Costs: Purchasing and holding vast inventories of fast-moving goods ties up credit facilities and incurs rising borrowing costs (especially amid elevated SAIBOR benchmarks).
  • Logistics, Handling & Warehousing Friction: Storage, freight, restocking, returns, and shrinkage that scale exponentially with physical shipment volume.
  • Cumulative Distribution Rebates: Volume discounts, listing fees, and promotional allowances granted to retailers and key accounts that strip away gross profit.
  • Opportunity Cost: Customer service and fulfillment bandwidth consumed by low-margin volume products instead of high-value, high-margin strategic offerings.

“It doesn't matter how many units leave the warehouse. What matters is the cash that stays in your corporate account after accounting for full absorption costing. Volume growth without profitability is the fastest route to insolvency.”

— Profitability Advisory & Unit Economics Practice, ISAR COMMUNITY

The Strategic Solution: Contribution Margin Matrix & Unit Economics

To regain mastery over corporate profitability, companies must institute rigorous Contribution Margin (CM) segmentation for every SKU:

  1. Deconstruct True Unit Economics: Calculate direct and indirect costs, assigning warehouse, shipping, debt-carrying, and sales commissions accurately to each unit sold.
  2. Classify Your Product Portfolio:
    • Value Drivers: High margin and robust profit generation, even if overall volume is moderate.
    • Balanced Anchors: Healthy margins contributing reliably to fixed operational overhead.
    • Cash Traps: High-velocity lines that generate substantial gross turnover but post net negative returns after operating expenses.
  3. Value-Based Repricing: Eliminate emotional and copycat pricing. Shift toward dynamic, margin-protective pricing structures calibrated for market resilience.

How ISAR COMMUNITY Solves This Challenge for Your Enterprise

At ISAR COMMUNITY, we look beyond high-level P&L summaries to audit the granular mechanics of your operational pipeline:

  • Comprehensive Cost Structure Audit: Pinpointing precisely where margins leak and identifying which product lines subsidize or drain enterprise equity.
  • Pricing Strategy & Margin Re-engineering: Designing agile pricing models that protect gross margins against inflation and supply chain volatility.
  • Capital & Resource Reallocation: Empowering commercial teams to focus capital on products and services generating the highest Return on Invested Capital (ROIC).

Are high sales volumes failing to translate into healthy net margins?

The senior financial advisory team at ISAR COMMUNITY provides an immediate forensic diagnostic of your product portfolio, helping you eliminate profit leakage and optimize your pricing for sustainable, institutional-grade profitability.

Book a Profitability Advisory Consultation